by Mark Smiley
For TruSox owner Dave Banning, the idea seemed simple: donate socks and gloves his company could not sell to people who needed them. Instead, he says, Colorado tax rules made giving the merchandise away more expensive than throwing it in the trash. The experience became one example of the regulatory frustrations that eventually prompted him to move his company’s Colorado operations to Kentucky.
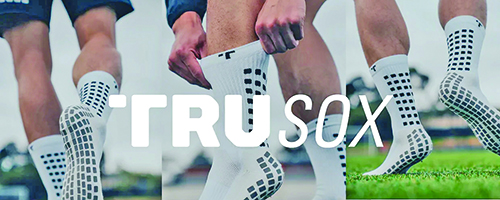
TruSox makes premium performance socks with proprietary grip technology designed to keep athletes’ feet stable inside their shoes. Its products are used by professional and other high-level athletes. The socks retail for about $55 a pair, or $70 for a wool version, and Banning insists that customers receive flawless merchandise.
During manufacturing, heat can reveal imperfections in the knitted socks. Banning estimates that 3% to 4% of merchandise becomes unsuitable for retail sale. The company also had excess ski gloves, including perfectly usable sizes retailers no longer wanted. Rather than discount those products and potentially undermine his brand, Banning wanted to donate them to homeless shelters.
That is where he encountered Colorado’s use-tax rules. TruSox purchases socks as inventory intended for resale, without paying sales tax at that stage. According to Banning, when the company removes merchandise from inventory to donate it, the state treats that as a taxable use. Discarding the same merchandise, he says, would not trigger the additional tax.
The distinction struck Banning as absurd. His company had already lost its investment in products it could not sell. Donating them could add a tax bill to that loss. “Why would I pay additional tax?” he asked. “I’m losing every penny I have in this product.”
Banning understands why rules prevent businesses from buying goods tax-free and then using them for their own benefit. But he questions applying the same treatment to unsellable goods handed to a nonprofit. “No one could explain what ‘use’ my business received for goods that we were wanting to donate,” he said in a follow-up email. “We were losing 100% of our investment to begin with, much less an additional ‘use’ tax levied by the state.”
He sought help from state Sens. Jeff Bridges and Lisa Cutter. Banning stresses that both lawmakers took his concerns seriously and worked diligently to find an answer. Over roughly a year and a half, he says, they communicated with the Colorado Department of Revenue, trying to clarify the rules and identify a practical solution.
“They were really good about trying to figure out what and why all this,” Banning said. He does not consider the dispute partisan and does not blame either senator for the outcome.
Instead, he says the experience raised a larger question about accountability in state government. “One of the central issues is elected officials not being able to get results from unelected bureaucrats that are writing and imposing regulations that were passed by the same elected officials,” Banning wrote. “It appears these bureaucrats have more power than the elected officials.”
Banning said he was told the state collected more than $1 million annually through this category of taxation and was reluctant to surrender that revenue. He also recalls Bridges recognizing the irony: public programs may spend money securing socks and gloves for shelters while a company offering similar goods for free faces a tax consequence.
One proposed workaround, Banning said, was to accumulate $10,000 worth of seconds before donating them. But storing that much unsellable merchandise would consume warehouse space. He wanted to deliver a box or two to a shelter as items accumulated, not stockpile pallets waiting to meet a threshold.
“I wanna drop a box once a week at the shelter when they need it,” he said. He wasn’t seeking a special financial benefit, he added, only a way to keep useful products out of landfills and get them to people who could use them.
The tax dispute was not the sole reason TruSox left Colorado. Banning cites an accumulation of regulations and employment costs that made competing with companies in other states increasingly difficult. He does not necessarily oppose measures such as paid family leave in principle, but says their costs matter to businesses competing nationally.
By Banning’s estimate, 99.9% of TruSox’s business was outside Colorado. He kept operations here largely because he grew up in the state. Ev
entually, that personal connection was not enough. About two years ago, he moved production to Kentucky. TruSox now has no Colorado employees.
The departure eliminated approximately 15 to 20 local jobs, many of them entry-level production and shipping positions. B
anning knows one small company’s move will not dramatically alter the state’s economy. His concern is what happens when many employers make the same calculation.
“The state’s not gonna miss my 15 or 20 dinky little jobs,” he said. “But if there’s enough people like me that say, ‘We’re done, we’re out,’ you’re gonna start seeing it.”
Unlike restaurants or repair shops that depend on local customers, manufacturers serving national markets can relocate production and shipping. Banning believes policymakers should consider the cumulative consequences of those decisions.
“It’ll be 20 here and 40 there and 10 here and five there,” he said. For TruSox, the decision is final. “I finally had enough.”